Asset Allocation, The Blueprint of Investing


Get data-backed market insights
Well-researched articles on markets, equities, mutual funds and investing, delivered to your inbox.
Most investors enter the market thinking the key to success lies in selecting the right stock or the best mutual fund. This leads them to constantly chase performance, switching investments based on recent returns. However, over time, many realize that even after choosing “good” investments, their overall portfolio performance remains inconsistent.
The real reason behind this inconsistency is not poor stock selection, but poor allocation of capital.
Asset allocation is the framework that decides how your money is distributed across different asset classes. It determines how your portfolio behaves during market ups and downs, how much risk you are exposed to, and whether you will stay invested long enough to achieve your financial goals.
Instead of focusing on predicting markets, asset allocation focuses on preparing for them.
What is Asset Allocation
Asset allocation is not just diversification. It is a deliberate strategy of combining different assets that react differently to economic conditions.
Each asset class has a different purpose:

When you combine them, you are not just spreading money. You are designing a system where:
- One asset grows
- One stabilizes
- One protects during crisis
Why Most Investors Fail Without Asset Allocation
Most retail investors unknowingly follow a concentrated strategy, especially in India where equity investing is heavily promoted.
Common pattern:
- Market rises → Investor increases equity exposure
- Market falls → Investor exits completely
This creates a cycle of:
- Buying high, Selling low
Problem:
- Without allocation, your portfolio becomes dependent on timing, which is extremely difficult to get right consistently.
Case Study 1: Aggressive Without Structure
Investor: Rahul (Age 27)
- Allocation: 100% Equity
- Market phase: Bull run
Rahul’s portfolio grows rapidly. Confidence increases.
Then market corrects by 30%, Portfolio falls sharply, No defensive asset to cushion, Emotional pressure builds, Exits at loss
Outcome: Loss + missed recovery + broken confidence
Case Study 2: Structured Asset Allocation

- When market falls: Equity declines, Debt remains stable, Gold may rise
Overall portfolio fall: Controlled
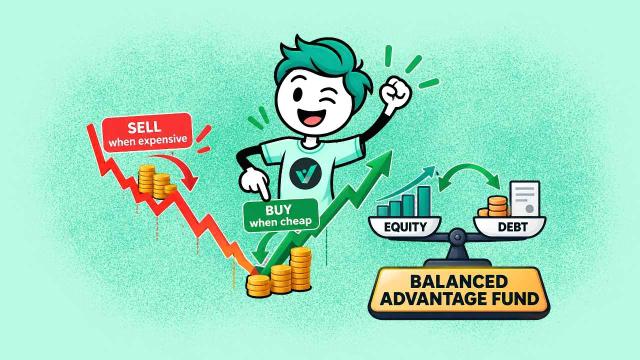
Now rebalancing happens: Sell some debt/gold, Buy equity at lower prices
Outcome: Faster recovery, Higher long-term returns, Lower emotional stress
The Power of Rebalancing, where the real Alpha Comes
Over time, allocations shift.
Example: Equity performs well → becomes 80% instead of 70%
Rebalancing means:
Selling excess equity, Adding to debt/gold
What this does:
- Selling equity after rise = Booking high
- Buying underperforming asset = Entering low
This is one of the few systematic ways to “buy low, sell high” without timing the market.
How to Decide Your Asset Allocation

Role of Each Asset
Equity, Growth Engine
Equity is essential for beating inflation and building wealth. However, its volatility means it should not dominate your portfolio beyond your risk capacity.
Use: Index funds, Diversified mutual funds, Direct stocks
Debt, Stability Anchor
Debt provides predictability. It ensures that not all your capital is exposed to market swings.
Use: Debt mutual funds, Bonds, Fixed deposits
Gold, Crisis Hedge
Gold is not a return-generating asset in normal times. Its real value emerges during:
Economic uncertainty, Currency weakness, Market crashes
Use: Gold ETFs, Sovereign Gold Bonds
Real Estate, Optional Diversifier
Real estate adds diversification but has:
- Low liquidity
- High ticket size
For most investors, exposure via REITs is more practical.
- Common Mistakes You Must Avoid Over-diversification, Too many funds without strategy, Ignoring rebalancing, Copying others’ allocation, All-in equity during bull markets
Final Thoughts
Asset allocation is not about maximizing returns in the short term. It is about ensuring that your portfolio survives all market conditions and still delivers consistent growth over time.
Book a free Consultation call With Vinca Wealth, So we can help you in building right Asset allocation according to your needs.
Frequently Asked Questions
Is Vinca Wealth registered?
Yes. Vinca Wealth is an AMFI registered mutual fund distributor (ARN-293401), based in Bengaluru, Karnataka. Our company CIN is U65999KA2022PTC169569, and our Insurance POSP Code is 1726204591.
Do I have to pay Vinca Wealth any fee?
No. We don’t charge you a fee for planning or investing. As a mutual fund distributor, we receive a commission from the fund houses whose schemes you invest in, and we disclose this upfront. You invest directly from your bank account to the fund house; your money never passes through Vinca Wealth.
How can I find out if I’m on track for retirement?
Start with our free Financial Freedom Calculator on vincawealth.com. In about 2 minutes it estimates your retirement corpus, your gap and your projected retirement date. You can then book a one-on-one session with our team to build a goal-based plan.
Can I meet the Vinca Wealth team?
Yes. We meet clients one-on-one at our office in Bengaluru or at a place of your choice in Bengaluru. If you live in another city or outside India, we connect over a video call.