How to Build a Retirement Plan for Parents in India
Work out your parents monthly gap, protect their health, and keep your own retirement on track


Get data-backed market insights
Well-researched articles on markets, equities, mutual funds and investing, delivered to your inbox.
Every month, many young earners in Bengaluru send money home to parents in Hubballi, Mysuru, Patna or Kochi. The transfer feels simple, but there is rarely a plan behind it. Nobody knows how big that amount must become in five years, or what happens if a parent lands in hospital. A retirement plan for parents in India answers these questions with a few clear numbers. 🤔
You are far from alone in this. This guide builds the plan in five clear steps, and it includes the part most guides skip, which is your own retirement.
How do you build a retirement plan for parents in India?
Build it in five steps, Find your parents monthly gap and set up steady income from their savings. Then protect them from big hospital bills, keep your own retirement savings going, and sort out nominations and a will. Do them in this order, because each step changes the size of the next one.
Most families start from the wrong end. They pick a product first, often a pension policy someone at the bank suggests, and then hope it fits. A plan works the other way round, like booking train tickets for the whole family. You check who is travelling and when, before you choose the train. 🙂
So the first step is a conversation, not a spreadsheet. Sit with your parents and list what they spend, what comes in, what they own and what they owe. Many parents find this talk awkward because they do not want to be a burden, so keep it calm and practical.
Why do so many parents in India need their children's help after retirement?
Many Indian parents worked in jobs without a pension, and their savings went into a house, education and weddings. Nearly 70% of India's elderly are financially dependent, according to a 2025 report using national ageing survey data. Longer lives and fast rising medical costs make the gap bigger every year.
The 70% figure comes from a 2025 Sankala Foundation report with NITI Aayog, based on the Longitudinal Ageing Study in India. Headlines turned it into 70% of Indian parents cannot retire. The report actually counts two groups, people who depend on family and people who keep working past 60 just to manage.
The UNFPA India Ageing Report 2023 adds more detail. More than 40% of elderly Indians are in the poorest fifth of households by wealth, and about 18.7% have no income at all. 😢 The same report expects people over 60 to make up 20.8% of India's population by 2050, up from 10.5% in 2022.
Two more forces make this harder. First, people live longer. A 60-year-old in India can expect to live about 18 to 19 more years on average, and many live longer. Second, medical costs rise faster than other prices, and Aon expects medical costs in India to rise 11.5% in 2026 and 10.1% in 2027.
How much money do your parents actually need each month?
Your parents need enough to cover their monthly gap, which is what they spend minus what they already earn from pension, rent or interest. Work it out for today, then for 5 and 10 years ahead. At 7% inflation, monthly costs roughly double in about 10 years.
Take an example: Arjun, a 28-year-old software engineer in Bengaluru . His parents live in Hubballi, and his father, 62, retired from a private company with no pension. The family has ₹20 lakh from provident fund and gratuity, plus ₹8,000 a month in rent from a small shop. Household costs, including medicines, come to about ₹30,000 a month.
Say the ₹20 lakh goes into the Senior Citizens Savings Scheme, or SCSS, at the current 8.2% a year. That works out to about ₹13,700 a month, paid once every quarter. Add the rent, and the parents earn about ₹21,700 a month. So today, Arjun needs to send only about ₹8,300 a month.
Here is the part most guides skip. SCSS pays a fixed rate for five years, and shop rent rarely keeps pace with prices. Look at what 7% inflation does to Arjun's share.
| When | Monthly cost | Parents' own income | Arjun's share |
|---|---|---|---|
| Today | ₹30,000 | ₹21,700 | ₹8,300 |
| In 5 years | ₹42,100 | ₹21,700 | ₹20,400 |
| In 10 years | ₹59,000 | ₹21,700 | ₹37,300 |
Illustration only, not a projection. It assumes 7% yearly inflation, the SCSS rate staying at 8.2% on renewal, and rent that does not rise.
In 10 years, Arjun's share becomes more than four times today's amount, even though the interest and rent look the same on paper. That is not an interest rate problem, it is an inflation problem. So plan for at least 25 years of support, until your parents are around 90.
How can your parents get a steady monthly income from their savings?
Split their savings into three buckets. Keep one to two years of expenses in a bank account or FD for easy access. Put the next five years of income in government-backed schemes like SCSS and POMIS or short-term debt funds. Keep a small growth part in hybrid or equity funds, drawn later through an SWP.
The first bucket sits in a savings account, an FD linked to it, or a liquid fund, which is a very short-term debt fund. Money here is available within a day or two. It is the family's first defence when a hospital asks for a deposit.
For the second bucket, SCSS pays 8.2% a year for the October to December 2026 quarter. Anyone aged 60 or above can invest up to ₹30 lakh in it for five years. POMIS, the Post Office Monthly Income Scheme, pays 7.4% a year every month, up to ₹9 lakh for one person and ₹15 lakh for a joint account. Interest from both is taxed at your parents' normal income tax rate.
The third bucket holds money needed after five to seven years. A small part in hybrid funds, which mix shares and bonds, or equity mutual funds can grow faster than prices, though its value will rise and fall. Later, a Systematic Withdrawal Plan, or SWP, turns it into a monthly payment, the opposite of a SIP. Our guide to the SWP bucket strategy for retirement income explains how to refill the buckets.
An SWP for parents' monthly income also has a tax edge, because tax applies only to the profit part of each withdrawal. For equity funds held over a year, the first ₹1.25 lakh of gains each year is tax-free, and the rest is taxed at 12.5%.
Should the savings be in your name or your parents' name?
Money you give your parents counts as a gift from a relative, so it is not taxed. Once it is truly theirs, its interest is generally taxed as their income. Under the new tax regime, a resident with taxable income up to ₹12 lakh pays no income tax because of a rebate. So the same interest may attract less tax in their hands.
Watch two things. If the money keeps flowing back to you, the tax benefit can be lost. And a gift becomes your parents' property, so it passes through their will or inheritance law, and siblings may have an equal claim even if you are the nominee. So either keep the savings in your name and send a fixed amount monthly, or gift it properly and make sure your parents have a will.
Can you support your parents without hurting your own retirement?
Yes, if you treat your own retirement savings as a fixed bill, like rent. A common mistake in the sandwich generation, people supporting parents and children at once, is to pause their own SIPs first. That feels harmless, but the early years you skip are when your money grows the most, because returns keep earning returns.
Airlines ask you to wear your own oxygen mask first, and money works the same way. Stop saving for yourself, and your own children may face this same problem 30 years from now.
Go back to Arjun. Say he invests ₹10,000 a month in a SIP from 28 to 58, growing at an assumed 10% a year. He would have about ₹2.28 crore. If he skips the first five years, he would have about ₹1.34 crore. He invests only ₹6 lakh less but ends with about ₹94 lakh less, a drop of about 41%. This is an illustration, not a projection, and our article on the benefits of starting a SIP early explains why time matters.
Fix two amounts each month, one for your parents and one for your own retirement, and protect both like EMIs. If you have siblings, agree on each share in writing, which saves long family WhatsApp debates about who paid for the last hospital visit.
Before you fix how much to send home each month, check that your own future is covered. The real question is how far your savings are from the amount you will need one day. Our Financial Freedom Score shows you that in about two minutes, along with the monthly SIP that would close any gap.
How do you protect parents above 60 from a big hospital bill?
Buy a separate health policy for your parents as early as possible, while they are healthier. Since April 2024, there is no upper age limit to buy health insurance in India. Keep an emergency fund for costs the policy will not pay, and parents aged 70 or above can also get Ayushman Bharat cover.
One hospital stay can undo years of saving. National ageing survey data shows that about 35.6% of people over 60 have heart or blood vessel disease, and 13.2% have diabetes. With medical costs rising about 10% a year, health insurance for parents above 60 is the wall that protects the rest of the plan.
In April 2024, the insurance regulator IRDAI removed the old age limit of 65 for buying a new policy. It also cut the longest waiting period for existing illnesses from four years to three. Since January 2025, insurers need IRDAI's approval to raise senior citizens' premiums by more than 10% a year.
When comparing policies, look past the premium. Check the co-payment, which is the share of each bill your parents pay themselves, and any limits on room rent. A super top-up, which pays only after a bill crosses a set amount, can raise the cover at a lower cost. Our list of health insurance mistakes that lead to claim rejection is worth a look before you sign.
For parents aged 70 or above, Ayushman Bharat gives ₹5 lakh of health cover a year, whatever their income. It works only at hospitals listed under the scheme, so treat it as a base, not the whole plan.
What should your parents' retirement plan include, and what should you avoid?
It should include a clear monthly gap, three income buckets, separate health cover, an emergency fund and updated nominations. Avoid locking everything in one product, signing up for long lock-ins you do not fully understand, and stopping your own retirement savings to fill the gap.
Paperwork is the step families leave for later, and later often arrives at a hospital. Under SEBI's revised rules, a mutual fund account, or folio, can have up to 10 nominees, and since November 2025, bank deposits can have up to four. A nominee, the person named to receive the money, can claim it easily, but legal heirs may still have a claim. Our guide to choosing between a will and a trust explains why a simple will matters too.
Nobody knows what interest rates or medical costs will be in 10 years, but a plan turns a vague worry into numbers you can review yearly. Use this checklist for where your family is today.
- Parents under 60, buy their health cover now while premiums are lower, and start the three buckets.
- Parents aged 60 to 70, use SCSS and POMIS for income and keep one to two years of costs within easy reach.
- Parents aged 70 or above, register them for Ayushman Bharat cover and keep more money in the first bucket.
- Siblings sharing costs, agree on each share in writing and use one shared account for parents' bills.
- Yourself, keep your own SIP and emergency fund running, and never take back money gifted to your parents.
This checklist covers most families, but your answer depends on your parents' savings, their health, your own goals and the funds you already hold. If you would like someone to look at how this applies to your family and your mutual funds, you can book a consultation with the Vinca Wealth team.
Frequently Asked Questions
Can I help my parents with a small salary?
Yes, Start with a health policy for them and a small emergency fund, because one hospital bill can cost more than years of monthly support.
Should I add my parents to my company health cover?
Yes, if your employer allows it, but treat it as extra. That cover usually ends when you leave the job, so keep a separate policy too.
Is SCSS enough for a retired couple's monthly expenses?
Usually not on its own. Its rate stays fixed for five years and the limit is ₹30 lakh per person, so it cannot keep pace with rising costs alone.
Should parents above 65 keep any money in equity funds?
A small part meant for needs seven or more years away can help keep up with inflation. Money needed in the next few years usually sits better in steadier options.
Is Vinca Wealth registered?
Yes. Vinca Wealth is an AMFI registered mutual fund distributor (ARN-293401), based in Bengaluru, Karnataka. Our company CIN is U65999KA2022PTC169569, and our Insurance POSP Code is 1726204591.
Do I have to pay Vinca Wealth any fee?
No. We don’t charge you a fee for planning or investing. As a mutual fund distributor, we receive a commission from the fund houses whose schemes you invest in, and we disclose this upfront. You invest directly from your bank account to the fund house; your money never passes through Vinca Wealth.
How can I find out if I’m on track for retirement?
Start with our free Financial Freedom Calculator on vincawealth.com. In about 2 minutes it estimates your retirement corpus, your gap and your projected retirement date. You can then book a one-on-one session with our team to build a goal-based plan.
Can I meet the Vinca Wealth team?
Yes. We meet clients one-on-one at our office in Bengaluru or at a place of your choice in Bengaluru. If you live in another city or outside India, we connect over a video call.
Related Articles
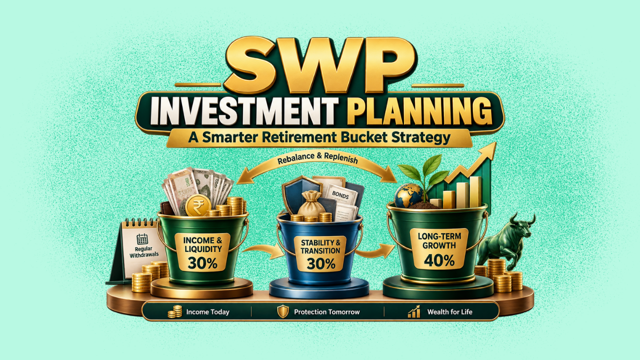
SWP Investment Planning, A Retirement Bucket Strategy for Sustainable Income
NPS, A Complete Guide to Investment Options, Tax Benefits, Withdrawals and the New Retirement Income Scheme